
Key takeaways
- The IPO’s success hinges on a dramatic financial turnaround that few observers predicted.
- Co-founder and CEO Luca Ferrari has articulated a philosophy that distinguishes Bending Spoons from venture-backed peers obsessed with product-market fit and rapid scaling.
- The IPO syndicate—led by Goldman Sachs Inter national, JPMorgan, and Allen & Company—reflects institutional confidence that Bending Spoons’ model can sustain growth and profitability at scale.
- Bending Spoons’ trajectory from scrappy Milan-based Startup to $18 billion public company spans just over a decade.
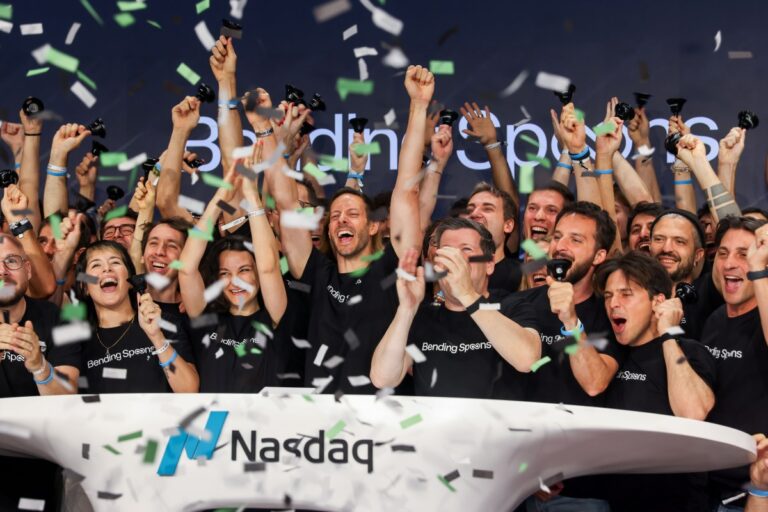
Bending Spoons priced its Nasdaq debut at $29 per share on June 30, 2026, raising $1.68 billion at an $18 billion valuation and beginning trading under ticker BSP on July 1. The Italian software roll-up, which owns 50+ digital brands including AOL, Eventbrite, Evernote, and Vimeo, exceeded its marketed range of $26–$28 per share, signaling strong institutional demand for its acquisition-driven growth model. The IPO marks a watershed moment for European Venture Capital and positions Bending Spoons as a new kind of technology powerhouse built on operational discipline rather than product innovation alone.
A Profitability Swing That Rewrote the Script
The IPO’s success hinges on a dramatic financial turnaround that few observers predicted. In Q1 2026, Bending Spoons reported $601.3 million in revenue alongside $27.5 million in net income, a stunning reversal from a $112.2 million net loss in the same quarter one year prior. This marks the company’s first full quarter of profitability, driven by margin improvements cascading across its sprawling portfolio of acquired brands.
The revenue base itself reflects aggressive consolidation. Bending Spoons serves 500 million monthly active users across its portfolio, with 93% of 2025 revenue derived from subscription models—a composition that underscores the stability of its cash flows. In Q1 2026 alone, the company deployed $2 billion in acquisition capital, a pace that dwarfs its historical spending; for context, Bending Spoons spent only $194 million on acquisitions throughout all of 2023.
A Founder’s Philosophy: Operational Excellence Over Chance
Co-founder and CEO Luca Ferrari has articulated a philosophy that distinguishes Bending Spoons from venture-backed peers obsessed with product-market fit and rapid scaling. In remarks released as the company filed for its IPO, Ferrari stated that “luck plays a big role in finding PMF—luck is irrelevant when pursuing operational excellence.” This mindset explains why Bending Spoons targets underperforming, established brands rather than chasing moonshot bets.
The philosophy has shaped a distinctive corporate strategy. Rather than building from scratch, Bending Spoons acquires mature digital properties with existing user bases and revenue streams, then applies centralized operations and AI-driven efficiency improvements to unlock margin expansion. The company has identified over 1,000 potential acquisition targets representing $400 billion in annual revenue, suggesting the roll-up thesis remains in its early innings.
Wall Street’s Heavyweight Bet on the Model
The IPO syndicate—led by Goldman Sachs International, JPMorgan, and Allen & Company—reflects institutional confidence that Bending Spoons’ model can sustain growth and profitability at scale. These underwriters typically anchor only offerings they believe will perform well in the secondary market, signaling that major banks see durable demand for the company’s shares.
The valuation itself carries implications for how the market views software roll-ups. Bending Spoons prices at 11x sales, a multiple that exceeds many quality software operators and sits above historical multiples commanded by Constellation Software, the most successful software roll-up of the past two decades. This premium pricing reflects investor conviction that Bending Spoons can replicate Constellation’s track record of serial acquisitions, integration discipline, and consistent value creation.
From Startup Scraps to European Decacorn
Bending Spoons’ trajectory from scrappy Milan-based Startup to $18 billion public company spans just over a decade. Co-founders Luca Ferrari and Matteo Danieli launched the company in 2013 after their previous venture, Evertale, failed—they bootstrapped the initial effort with $40,000 from that defunct project. Early homegrown successes like Splice provided proof of concept before the company pivoted to its now-dominant acquisition strategy.
In October 2025, three months before the IPO, Bending Spoons raised $710 million in equity at an $11 billion pre-money valuation, plus a $2.8 billion debt package, cementing its status as Italy’s first decacorn. That round was led by T. Rowe Price with participation from Baillie Gifford, Durable Capital, and Fidelity—a roster of blue-chip investors that validated the company’s path to profitability and public markets.
The Scale Test Ahead
Bending Spoons now faces the critical challenge of proving its model works at much larger scale. The company must continue acquiring targets while maintaining the operational discipline and margin improvement that drove its recent profitability. The $400 billion addressable market of potential acquisition targets suggests runway, but execution risk remains—integrating dozens of acquired brands while preserving their user bases and revenue requires sustained operational excellence.
Investors will scrutinize quarterly results for signs that acquisition spending is translating into sustainable revenue growth and margin expansion. The IPO raises capital for continued M&A and provides Bending Spoons with currency to accelerate its roll-up strategy. Whether the company can sustain its $18 billion valuation will hinge on whether Ferrari’s operational philosophy—that luck is irrelevant in pursuit of excellence—holds true as Bending Spoons scales to become a global software conglomerate.
