
Key takeaways
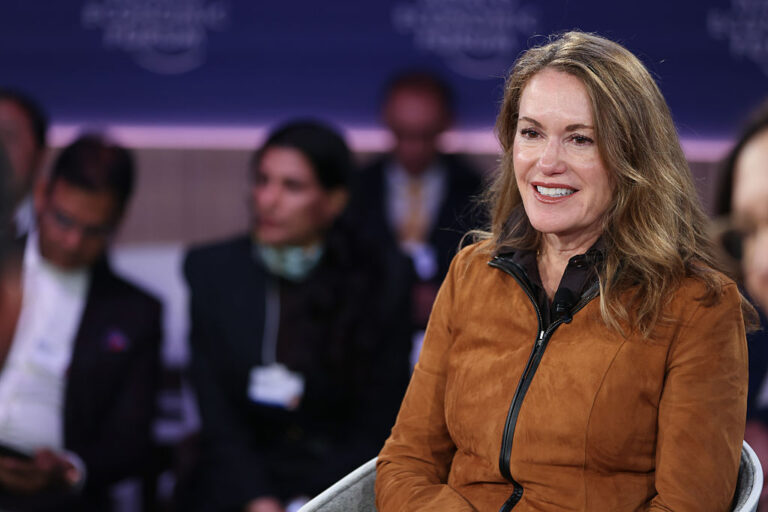
- CEO Peggy Johnson framed the public debut as a strategic milestone for U.S.
- Johnson has been explicit in recent media appearances that Agility’s immediate focus is workplace and industrial deployment to address acute labor shortages in warehouses, manufacturing, and logistics.
- Agility’s public debut arrives as the humanoid robotics sector transitions from laboratory demonstrations to commercial deployment at scale.
Agility Robotics announced on June 24, 2026, that it will become the first U.S.-listed pure-play humanoid robotics company with active commercial deployments, merging with Churchill Capital Corp XI (CCXI) in a deal valuing the company at $2.5 billion pre-money and generating over $620 million in gross proceeds. The combined entity will trade under the ticker “AGLT” and will be led by CEO Peggy Johnson, whose background scaling operations at Microsoft positions her to guide the transition from private R&D to public commercialization. The announcement marks a watershed moment for the robotics industry, yet company leadership is explicit: consumers should not expect humanoid robots in their homes anytime soon.
A Historic Milestone for Industrial Robotics
Agility Robotics’ path to public markets represents a significant inflection point for the humanoid robotics sector, which has accelerated faster than traditional capital-allocation frameworks anticipated between 2023 and 2026. The SPAC merger with Churchill Capital Corp XI will inject capital specifically earmarked for scaling production of the company’s Digit robot line, fulfilling existing customer orders, and advancing Digit v5 capabilities. The deal structure includes approximately $200 million from a PIPE (private investment in public equity) committed at $10 per share, supplementing the capital raised through the merger itself.
Unlike many competitors still piloting prototypes, Agility has already deployed hundreds of Digit robots with major commercial clients including Amazon and auto parts manufacturer Schaeffler. The company also counts GXO Logistics among its operational partners, demonstrating real-world traction in warehouse automation and industrial labor shortage mitigation. This commercial validation distinguishes Agility from well-funded but pre-revenue peers and anchors the company’s valuation in proven deployment rather than speculative technology hype.
Why This Matters: American Tech Leadership and Market Timing
CEO Peggy Johnson framed the public debut as a strategic milestone for U.S. technological leadership, stating that “humanoid robots are a critical driver of American technology leadership and the future of global technology.” This positioning reflects broader geopolitical competition in physical AI and automation, where the United States is competing against International robotics manufacturers for market dominance. The IPO signals to investors and policymakers alike that the humanoid robotics sector has matured beyond speculative venture funding and is ready for institutional capital markets scrutiny.
The timing is particularly significant given the global robotics landscape. According to the International Federation of Robotics, global robot installations crossed 590,000 units per year, though humanoid robots represent only a fraction of this base. This suggests Agility is entering a market inflection point where demand for humanoid systems is accelerating, and the capital markets are willing to fund scaling operations. The company’s commercial deployments provide measurable revenue and customer retention data—assets that traditional IPO investors demand.
Setting Expectations: Industrial First, Home Later
Johnson has been explicit in recent media appearances that Agility’s immediate focus is workplace and industrial deployment to address acute labor shortages in warehouses, manufacturing, and logistics. The company is not positioning Digit as a consumer product for household use, a positioning that aligns with industry consensus that home robotics remain a decade away from mainstream viability. The technology is currently optimized for structured environments with predictable workflows—precisely the conditions where Amazon warehouses and Schaeffler manufacturing facilities operate.
This reality check is important for retail investors entering positions in AGLT post-listing. The bull case for Agility rests on industrial automation scaling, not the sci-fi narrative of humanoid household companions. The $620 million in proceeds will accelerate production ramp and customer fulfillment, not pivot the company toward consumer markets. Insiders have demonstrated conviction in this strategy: 100% of existing Agility shareholders are rolling equity into the combined company, and all insiders are subject to a 180-day lockup period, preventing immediate cash-outs at the public market’s expense.
Agility’s Valuation in Context: Smaller Than Figure, Larger Than the Category
Agility’s $2.5 billion pre-money valuation is substantially smaller than Figure AI’s $39 billion private valuation following a $1 billion Series C round in September 2025, which attracted investors including Microsoft, NVIDIA, and Jeff Bezos. However, this gap reflects a fundamental difference in maturity: Figure is still in pilot phases with customers like BMW, while Agility has hundreds of robots deployed and generating revenue. The market is pricing Agility based on proven commercial traction rather than speculative technology potential, a distinction that separates the company from its well-funded but pre-revenue peers.
The SPAC structure itself is notable. Rather than pursuing a traditional IPO with full SEC disclosure obligations, Agility opted for a merger with Churchill Capital Corp XI—a path that offers a streamlined timeline and reduced regulatory friction. This approach is increasingly common for high-growth technology companies seeking public capital while maintaining operational flexibility, and it underscores how the capital markets are adapting to support emerging technology sectors.
The Sector’s Inflection Point
Agility’s public debut arrives as the humanoid robotics sector transitions from laboratory demonstrations to commercial deployment at scale. The company’s commercial deployments with Fortune 500 customers and logistics providers represent a validation milestone that most robotics Startups have not yet achieved. The sector has moved faster than traditional Venture Capital expected, forcing institutional investors to reassess their allocation frameworks and risk tolerances for physical AI companies.
The $620 million capital raise signals institutional confidence in the humanoid robotics market’s near-term growth trajectory. Global robot installations totaled 590,000 units annually, but humanoid systems are capturing an increasing share of new deployments as labor costs rise and supply chain resilience becomes a priority for large manufacturers. This structural tailwind is what attracted the PIPE investors and SPAC sponsors to the Agility transaction.
What Comes Next for Agility and the Industry
Investors will closely monitor Agility’s execution on three fronts: fulfilling the existing customer order book, ramping Digit v5 production, and expanding deployments beyond Amazon and Schaeffler to new enterprise customers. The company’s ability to demonstrate accelerating revenue and customer wins post-listing will determine whether AGLT attracts sustained institutional buying or faces the volatility typical of early-stage tech IPOs. The 180-day lockup period for insiders means that insider-selling pressure will not emerge until late 2026, providing a window for the company to demonstrate operational momentum.
Agility’s public listing will also serve as a market test for the broader humanoid robotics sector. Success will likely accelerate competing companies’ timelines toward capital markets, while underperformance could temper investor appetite for pure-play robotics companies. The first months of AGLT trading will reveal whether institutional capital is genuinely willing to fund the long development cycles and capital intensity that humanoid robotics demand, or whether the sector’s growth narrative has outpaced market reality. For now, Agility has demonstrated something most of its competitors have not: the ability to deploy robots at scale and generate customer revenue in the process.
