
Key takeaways
- Grindr's revenue has nearly tripled to $540M under Arison by raising per-user spending rather than aggressively expanding its user base, with pay conversion climbing from under 6% to above 9%.
- The company is testing an EDGE premium subscription tier and expanding into healthcare (ED medication, GLP-1s, PrEP information) and eventual telehealth partnerships, positioning these segments as potential major revenue sources within a decade.
- Despite 25%+ revenue growth for 16 consecutive quarters, Grindr trades at an 11x 2027 EBITDA multiple—roughly 35% below peers—which Arison attributes to investor stigma tied to the platform's identity as a gay dating app.
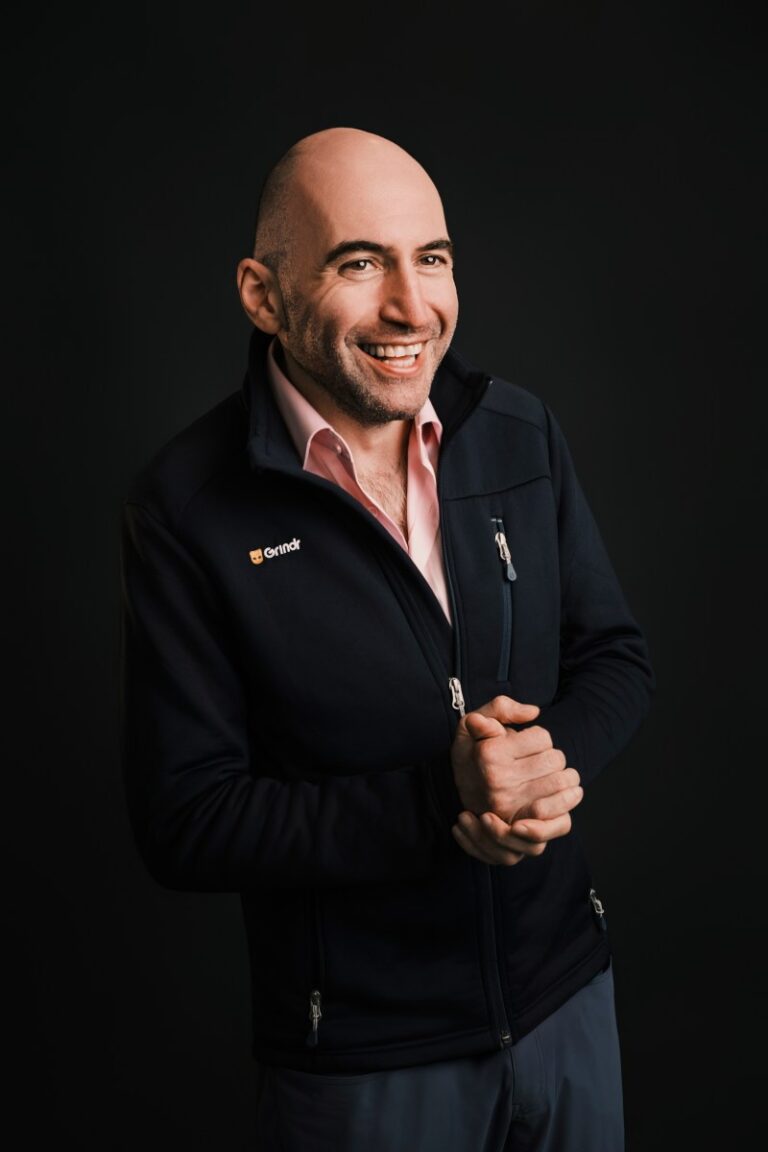
When George Arison arrived at Grindr in 2022, he found a company in disarray: profitable but directionless, shuffled through Chinese ownership, forced divestitures, and private-equity rescues. Four years later, Grindr has crystallized into a growth narrative that Wall Street is finally taking seriously. Revenue is on pace to reach $540 million or more this year, nearly tripling from $195 million in 2022. Adjusted EBITDA margins sit comfortably above 40%, signaling that the company is not just growing larger but doing so profitably.
The striking part of this expansion is its mechanics: Grindr has achieved it almost entirely by extracting more value from existing users rather than aggressively expanding its base. In the second quarter, the app had 1.4 million paying users representing roughly 9% of its total user base, but average revenue per user has climbed substantially since Arison took the helm. The pay conversion rate jumped from under 6% to above 9%, a metric Arison treats as a centerpiece of his operational strategy.
Rethinking the Dating App Playbook
The traditional dating-app formula pushes for user acquisition—bigger network, more matches, more engagement, better defensibility. Grindr has inverted this. Instead of chasing growth through scale, Arison is deepening monetization within an existing base and redefining what the platform sells.
That philosophy crystallized in the “gayborhood in your pocket” concept, a deliberate effort to expand Grindr beyond dating and casual encounters. The company now operates a healthcare division called Woodwork, offering cash-pay products including erectile dysfunction medications, GLP-1 weight-loss drugs, and peptides. Users can conduct these transactions directly in the app rather than being directed to an external website. An AI bot recently launched to automate the entire transaction flow.
HIV prevention and treatment form a second pillar: Grindr has committed to providing direct information access on PrEP availability to 10 million people, both domestically through an in-app health center and internationally. A third, more distant horizon involves telehealth partnerships connecting users with gay physicians—a service the company views as a potential major revenue stream within a decade, though it remains early-stage infrastructure work today.
The Premium Tier Bet and Pricing Strategy
EDGE and the Elasticity Test
Central to Grindr’s growth narrative is the upcoming EDGE subscription tier, positioned above the existing XTRA ($23.99 per month) and Unlimited ($44.99 per month) offerings. During testing in Canada, EDGE carried a price equivalent to roughly $350–375 in U.S. dollars per month—a figure that triggered ridicule on social media for exceeding the cost of traditional dating, let alone maintaining a relationship.
Arison frames the pricing skepticism as a misunderstanding of the test methodology. The company ran multiple price points to measure elasticity rather than settling on a final number. The tier itself does not sell artificial intelligence as a product; instead, it packages features built on AI—primarily advanced matching that uses behavioral data and intent signals to surface compatible partners the existing profile-based system would miss.
Retention metrics for these AI-driven matching features exceed any previous Grindr offering, according to Arison. The EDGE rollout is scheduled for late 2026 or early 2027, at which point the company expects to have crystallized pricing based on real market response. Arison compares the positioning to a Tesla Model S or X: a premium flagship now, with capabilities eventually percolating down to the broader user base.
Beyond Dating—AI Matching for Relationships
Grindr’s AI capabilities extend to a specific problem: the geographic constraints of dating. Even in San Francisco, where the concentration of gay residents is among the highest in the United States, the addressable market for an individual dating-app user is roughly 50,000 to 60,000 people. For smaller cities, the pool shrinks dramatically, a structural limitation that Arison identifies as central to why gay men report difficulty finding partners.
The EDGE tier’s most significant feature aims to dissolve these geographic barriers by surfacing high-compatibility matches across entire regions or countries, based on behavior rather than profile declarations. Arison acknowledges that Grindr cannot track whether these long-distance introductions result in lasting relationships—doing so would raise privacy concerns. The company’s rationale rests on observable shifts in what younger gay men seek: approximately 50% of gay men under 35 express interest in long-term monogamous relationships, and 25% want children—demographic desires that would have been rare in previous generations and that existing dating infrastructure has failed to accommodate.
The Persistent Valuation Discount
Despite the revenue trajectory and profitability, Grindr’s stock trades at a substantial discount relative to peers. At approximately 11 times 2027 EBITDA, the company’s valuation sits roughly 35% below comparable platforms. Arison attributes much of this gap to what he calls the “Grindr discount”—an explicit penalty applied by some institutional investors simply because the platform is a gay dating application.
He has cited instances of this discrimination in concrete terms: one investor presented a financial model to Arison with a line item literally labeled “Grindr discount” that knocked 25% off a fair-value calculation. During the Silicon Valley Bank crisis, Grindr struggled to access capital from major financial institutions, even as peers found willing partners. A consulting firm declined engagement over reputational concerns tied to the app’s core user base.
Recent market movement suggests some recalibration. Morgan Stanley upgraded Grindr to overweight in July, citing the EDGE tier and telehealth expansion. Goldman Sachs and Raymond James also raised price targets over the course of the year. The stock has climbed roughly a third over the past six months. Still, the discount persists, and whether it reflects genuine risk or enduring bias remains contested among analysts and investors.
Building at Scale Through AI
Arison’s operational footprint is minimal: 175 U.S. employees plus an offshore team in Colombia produces $540 million in annual revenue. This lean structure resulted from aggressive culling after his 2022 arrival—the company shed roughly 70% of its workforce when he instituted a two-days-per-week return-to-office policy in summer 2023, a decision that generated significant public backlash. Of the staff who were present when Arison arrived, only about 25 remain.
Within this lean organization, technical roles account for roughly 94 to 95 people. Arison credits artificial intelligence with enabling this compression. Approximately 80% of Grindr’s codebase is now written by AI systems. Over the past year, engineering productivity has increased 2.5 times. A reference from a large-tech CEO suggested that AI could substitute for 250 to 350 people through automation; Grindr’s experience aligns with that claim.
Revenue Diversification in Motion
Subscriptions currently represent 83% of Grindr’s revenue, down from 86% in 2022 despite subscription revenue itself growing substantially in absolute terms. The decline reflects the rising contribution of other sources—advertising, healthcare transactions, and miscellaneous services. For now, these non-subscription channels remain modest in scale. Arison’s decade-long vision positions Grindr as a company with four roughly equal revenue pillars: subscriptions, advertising, healthcare services, and travel-related offerings.
The healthcare business remains early, with no clinical telehealth partnerships operational today. Travel features, similarly, have not yet entered the product roadmap as a distinct offering. Arison is explicit that these expansions operate on a different time horizon than immediate quarterly performance, reflecting confidence in the platform’s capacity to evolve without sacrificing current profitability.
The Stigma Question Remains
When pressed on whether the valuation discount still applies, Arison acknowledges that market perception has shifted measurably, particularly after the recent rally and analyst upgrades. He argues that Grindr’s revenue growth—exceeding 25% for 16 consecutive quarters under his leadership—justifies treatment as a growth company. Yet he does not claim the stigma has vanished entirely.
The difference between Grindr and heterosexual dating platforms is revealing: Tinder, which prominently features a “free tonight” button on its homepage, faces no comparable discount despite offering transactional dating mechanics. The distinction, Arison suggests, reflects not dating controversy per se but discomfort specifically tied to gay identity and gay-focused commerce. Whether that dynamic will continue to constrain Grindr’s multiple as the company expands into healthcare and travel remains an open question for long-term investors.
Frequently Asked Questions
What is the EDGE tier and how much will it cost?
EDGE is a premium subscription tier positioned above XTRA ($23.99) and Unlimited ($44.99). During testing in Canada, it was priced around $350–375 CAD per month (roughly $260–280 USD), though Arison emphasized this was one test point among several to measure price elasticity. The final pricing will be set when EDGE launches in late 2026 or early 2027. The tier packages AI-driven features for improved matching based on behavioral data rather than selling AI itself.
How has Grindr achieved revenue growth without significantly expanding its user base?
Grindr has grown revenue from $195M (2022) to $540M+ (2026) primarily through increasing per-user spending. The company raised its pay conversion rate from under 6% to above 9%, and average revenue per user has risen considerably. In Q2 2026, Grindr had 1.4 million paying users representing 9% of its total user base. Meanwhile, subscriptions account for 83% of revenue, with newer businesses like healthcare and advertising forming smaller but growing revenue streams.
What is the 'Grindr discount' that Arison references?
Arison argues that some institutional investors apply an explicit valuation penalty to Grindr stock simply because it is a gay dating app. He cited an investor's financial model with a line item literally labeled "Grindr discount" that knocked 25% off fair-value estimates. The stock currently trades at roughly 11x 2027 EBITDA, approximately 35% below comparable platforms. Arison contends this reflects bias rather than financial risk, pointing to instances during the SVB crisis when Grindr struggled to access capital that peers obtained easily.
