
Key takeaways
- China's five largest humanoid robotmakers controlled 86 percent of global shipments in the first half of 2026, leveraging lower costs and manufacturing scale that U.S. competitors have not matched.
- U.S. tariffs on drones and robots starting in September aim to limit Chinese market access but do not address underlying cost advantages that compound over time through higher production volumes.
- Chinese manufacturers are shifting focus to price-sensitive markets in Europe, Southeast Asia and Latin America rather than competing in the restricted U.S. defense and security-focused robotics segment.
- Western manufacturers may retain competitive advantage in applications where security requirements matter more than cost, while Japan, South Korea and Taiwan explore regional alternatives to Chinese dominance.
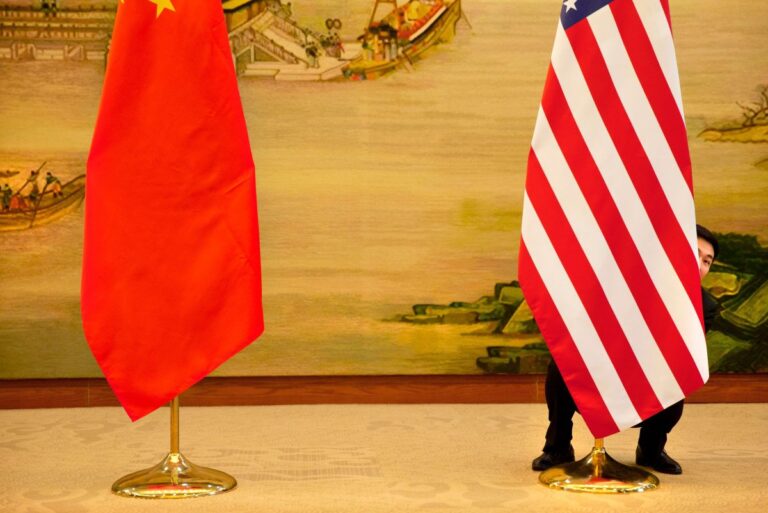
The United States is tightening its grip on foreign-made robotics and drones through tariffs and equipment restrictions, moves that formally take effect this fall. Yet analysts warn the barriers may merely redirect Chinese manufacturers to other parts of the world rather than slow their advance.
In July and August, Washington added drones and advanced robotic devices to its list of restricted imports on national-security grounds. Tariffs on drones arrive in September, with levies on components following in 2027. The restrictions are the latest expansion of the FCC’s Covered List, a framework first established in 2021 to block telecommunications and surveillance equipment from Chinese companies such as Huawei, ZTE and Hikvision.
The Scale of Chinese Dominance
Chinese manufacturers have built a commanding position in both sectors that U.S. and European competitors have struggled to match, particularly on price. In the first half of 2026 alone, global humanoid robot shipments reached 22,000 units, according to analysis by Counterpoint Research. The vast majority came from Chinese makers.
Market Leadership by Numbers
The world’s five largest humanoid robot manufacturers by volume are all Chinese: AgiBot, Unitree, Galbot, UBTECH and Leju Robotics. Together, these five companies accounted for 86 percent of global shipments in the first half of 2026. No American company appears on the list of top producers by volume. U.S. robotics firms operate at a significantly smaller manufacturing scale, according to Soumen Mandal, a principal analyst at Counterpoint Research.
Price and Production Advantages
The cost advantage compounds over time. Lower prices allow Chinese manufacturers to deploy more units in real-world settings, generating data that improves their technology. Higher production volumes simultaneously drive manufacturing costs down further, creating a reinforcing cycle that rivals find difficult to break. Unitree and other Chinese producers are also accelerating cost reductions by developing more components internally rather than sourcing them from outside suppliers. Meanwhile, automakers like XPeng leverage their existing expertise in semiconductor design and vehicle manufacturing as they enter the robotics market.
Why Cost Advantage Translates to Market Control
Ankur Saxena, an investment director at TDK Ventures, outlined the structural challenge facing Western competitors. “The United States leads in frontier AI, software and semiconductor innovation,” Saxena said. “China leads in manufacturing scale, supply-chain depth and cost.”
Unlike semiconductors, which can be controlled through limiting access to specific technologies, robotics does not rest on a single chokepoint component. Chinese competitors embedded across multiple parts of the supply chain make a complete domestic alternative infeasible. Saxena noted that tariffs alone cannot close a manufacturing cost gap that has taken years to develop.
Investment and Time Requirements
“You cannot sanction your way around a cost curve. You can only out-build it, and America has yet to begin making the decade-long investment that will require,” Saxena told TechCrunch. This observation captures a central tension: the restrictions imposed in Washington may protect domestic market share in the short term, but they do not directly address China’s global manufacturing advantages or production capacity.
Market Fragmentation Rather Than Clean Separation
Rather than creating a neat partition between American and Chinese robotics industries, the tariffs are likely to accelerate a shift toward regional markets, according to multiple industry participants. Bentzion Levinson, founder and CEO of Virginia-based drone maker Heven AeroTech, described an emerging split in the drone sector: one ecosystem built around U.S.-manufactured, NDAA-compliant systems for defense applications, and another centered on Chinese low-cost, high-volume production for consumer and commercial use.
Chinese robotics companies are already positioning themselves to capture markets beyond North America. They are targeting price-sensitive regions with labor shortages across Europe, Southeast Asia, Latin America and the Middle East, according to Mandal. The path mirrors the trajectory of Chinese electric-vehicle makers: build scale domestically, expand into foreign markets, establish local production facilities.
Regional Labor and Demographics
Countries facing labor shortages and demographic decline may emerge as early adopters of humanoid robots, particularly in manufacturing and repetitive-task roles. South Korea and Japan, facing their own labor challenges, could become both competitors and markets for this technology. South Korea’s Hyundai, which owns Boston Dynamics, and Japan’s Toyota are both investing in robotics, drawing on their automotive and manufacturing expertise. Taiwan remains a major semiconductor producer serving the broader robotics supply chain. Yet none of these countries can simply replace China’s embedded position in global component supply networks, Saxena observed.
Specialization by Region
Yang Fang of Beagle Technology, a California agtech startup using AI and robotics software to automate farm equipment, expects robotics to become increasingly regional as manufacturers design products for local labor markets and customer needs. Chinese companies may focus on products suited to China and neighboring markets, while U.S. firms build for North American industries.
Where Western Manufacturers Can Compete
The restrictions may carve out a narrower competitive space for U.S. and allied manufacturers. Agility Robotics, an American humanoid robot maker, welcomed the FCC’s decision in July, arguing that blocking foreign advanced robots before they embed deeply in the U.S. market—as has occurred with drones—could protect domestic development. The company produces its Digit humanoid in the United States and simultaneously advocates for continued access to the tools and technologies needed to advance robotics research.
Levinson suggests the next competitive arena will shift from drones themselves to the power systems and payload architecture they carry. Battery technology and energy limitations, he noted, could become the decisive competitive frontier as drones and robots become more capable.
The Allied Alternative
Saxena argued that competing with China does not require a purely domestic American supply chain. “The alternative to China isn’t a purely domestic U.S. supply chain; it’s a diversified allied one.” This framing points toward a strategy where the U.S. partners with Japan, South Korea and Taiwan to develop regional alternatives. Japan brings decades of industrial robotics and precision manufacturing expertise. South Korea contributes strength in electronics, batteries and automobiles. Taiwan anchors semiconductor supply.
Yet these countries cannot simply substitute for China’s manufacturing scale and cost position. Instead, they may occupy a middle ground between low-cost Chinese robots and expensive American offerings, offering security-conscious buyers an alternative that retains some cost advantage over fully domestic production.
Frequently Asked Questions
When do the U.S. tariffs on drones and robots take effect?
Tariffs on drones take effect in September 2026, with tariffs on drone components following in 2027. The restrictions expand the FCC's Covered List, first established in 2021.
Which Chinese companies lead the global humanoid robot market?
AgiBot, Unitree, Galbot, UBTECH and Leju Robotics account for 86 percent of global humanoid robot shipments in the first half of 2026, according to Counterpoint Research.
Why can't U.S. tariffs alone close the gap with Chinese robotics makers?
Chinese manufacturers have built durable cost and manufacturing advantages through scale, domestic supply chain depth and internal component development. These advantages compound over time as higher volumes drive costs lower, creating a cycle that tariffs alone cannot overcome.
