
Key takeaways
- Oura's $2.2 billion IPO is structured primarily to provide liquidity to existing shareholders, particularly Forerunner Ventures, rather than to raise capital for company operations.
- The company expects to use $526 million of the $532.6 million in net proceeds to pay employee equity tax obligations, leaving just $6.2 million for general purposes.
- Oura's subscription business—with 89% gross margins and revenue more than doubling to $240.5 million annually—is driving growth, with the company expecting 5.7 million members by year end.
- The company's valuation has jumped to approximately $14.1 billion at the IPO price midpoint, from $11 billion in October 2025 and $5.2 billion less than a year before.
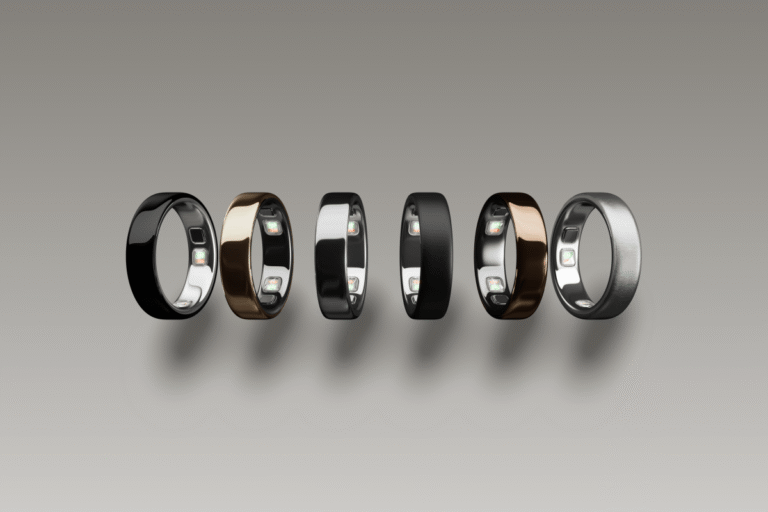
Oura, the Finnish smart ring maker, filed plans for an IPO that could raise as much as $2.2 billion, but the company itself will receive only a fraction of that capital. The deal structures 50 million shares at between $40 and $44 per share, with 36.5 million shares—nearly two-thirds—coming from existing shareholders seeking to liquidate their positions.
At the midpoint price of $42, shareholders would collect approximately $1.53 billion while Oura itself would pocket $567 million before underwriting fees and expenses. The split reveals the IPO to be less a capital-raising event and more an orchestrated exit for venture investors who backed the company through its critical early years.
Who Is Selling and Why
Forerunner Ventures dominates the share sale, capturing the majority of the proceeds headed to existing shareholders. The venture firm is liquidating its entire 9.3 percent stake—about 28.7 million shares—worth roughly $1.20 billion at the $42 midpoint. Those shares represent nearly eighty percent of all secondary shares being sold by existing shareholders in the deal.
Forerunner invested in Oura during the company’s 2020 Series B funding round, a $28 million raise. The firm is now realizing a substantial multiple on that early bet as Oura enters public markets. This level of concentration—with a single shareholder dominating the secondary offering—is uncommon; typically, IPO share sales are distributed among multiple early backers as each realizes their gains at different valuations and times.
What Oura Plans to Do With the Proceeds
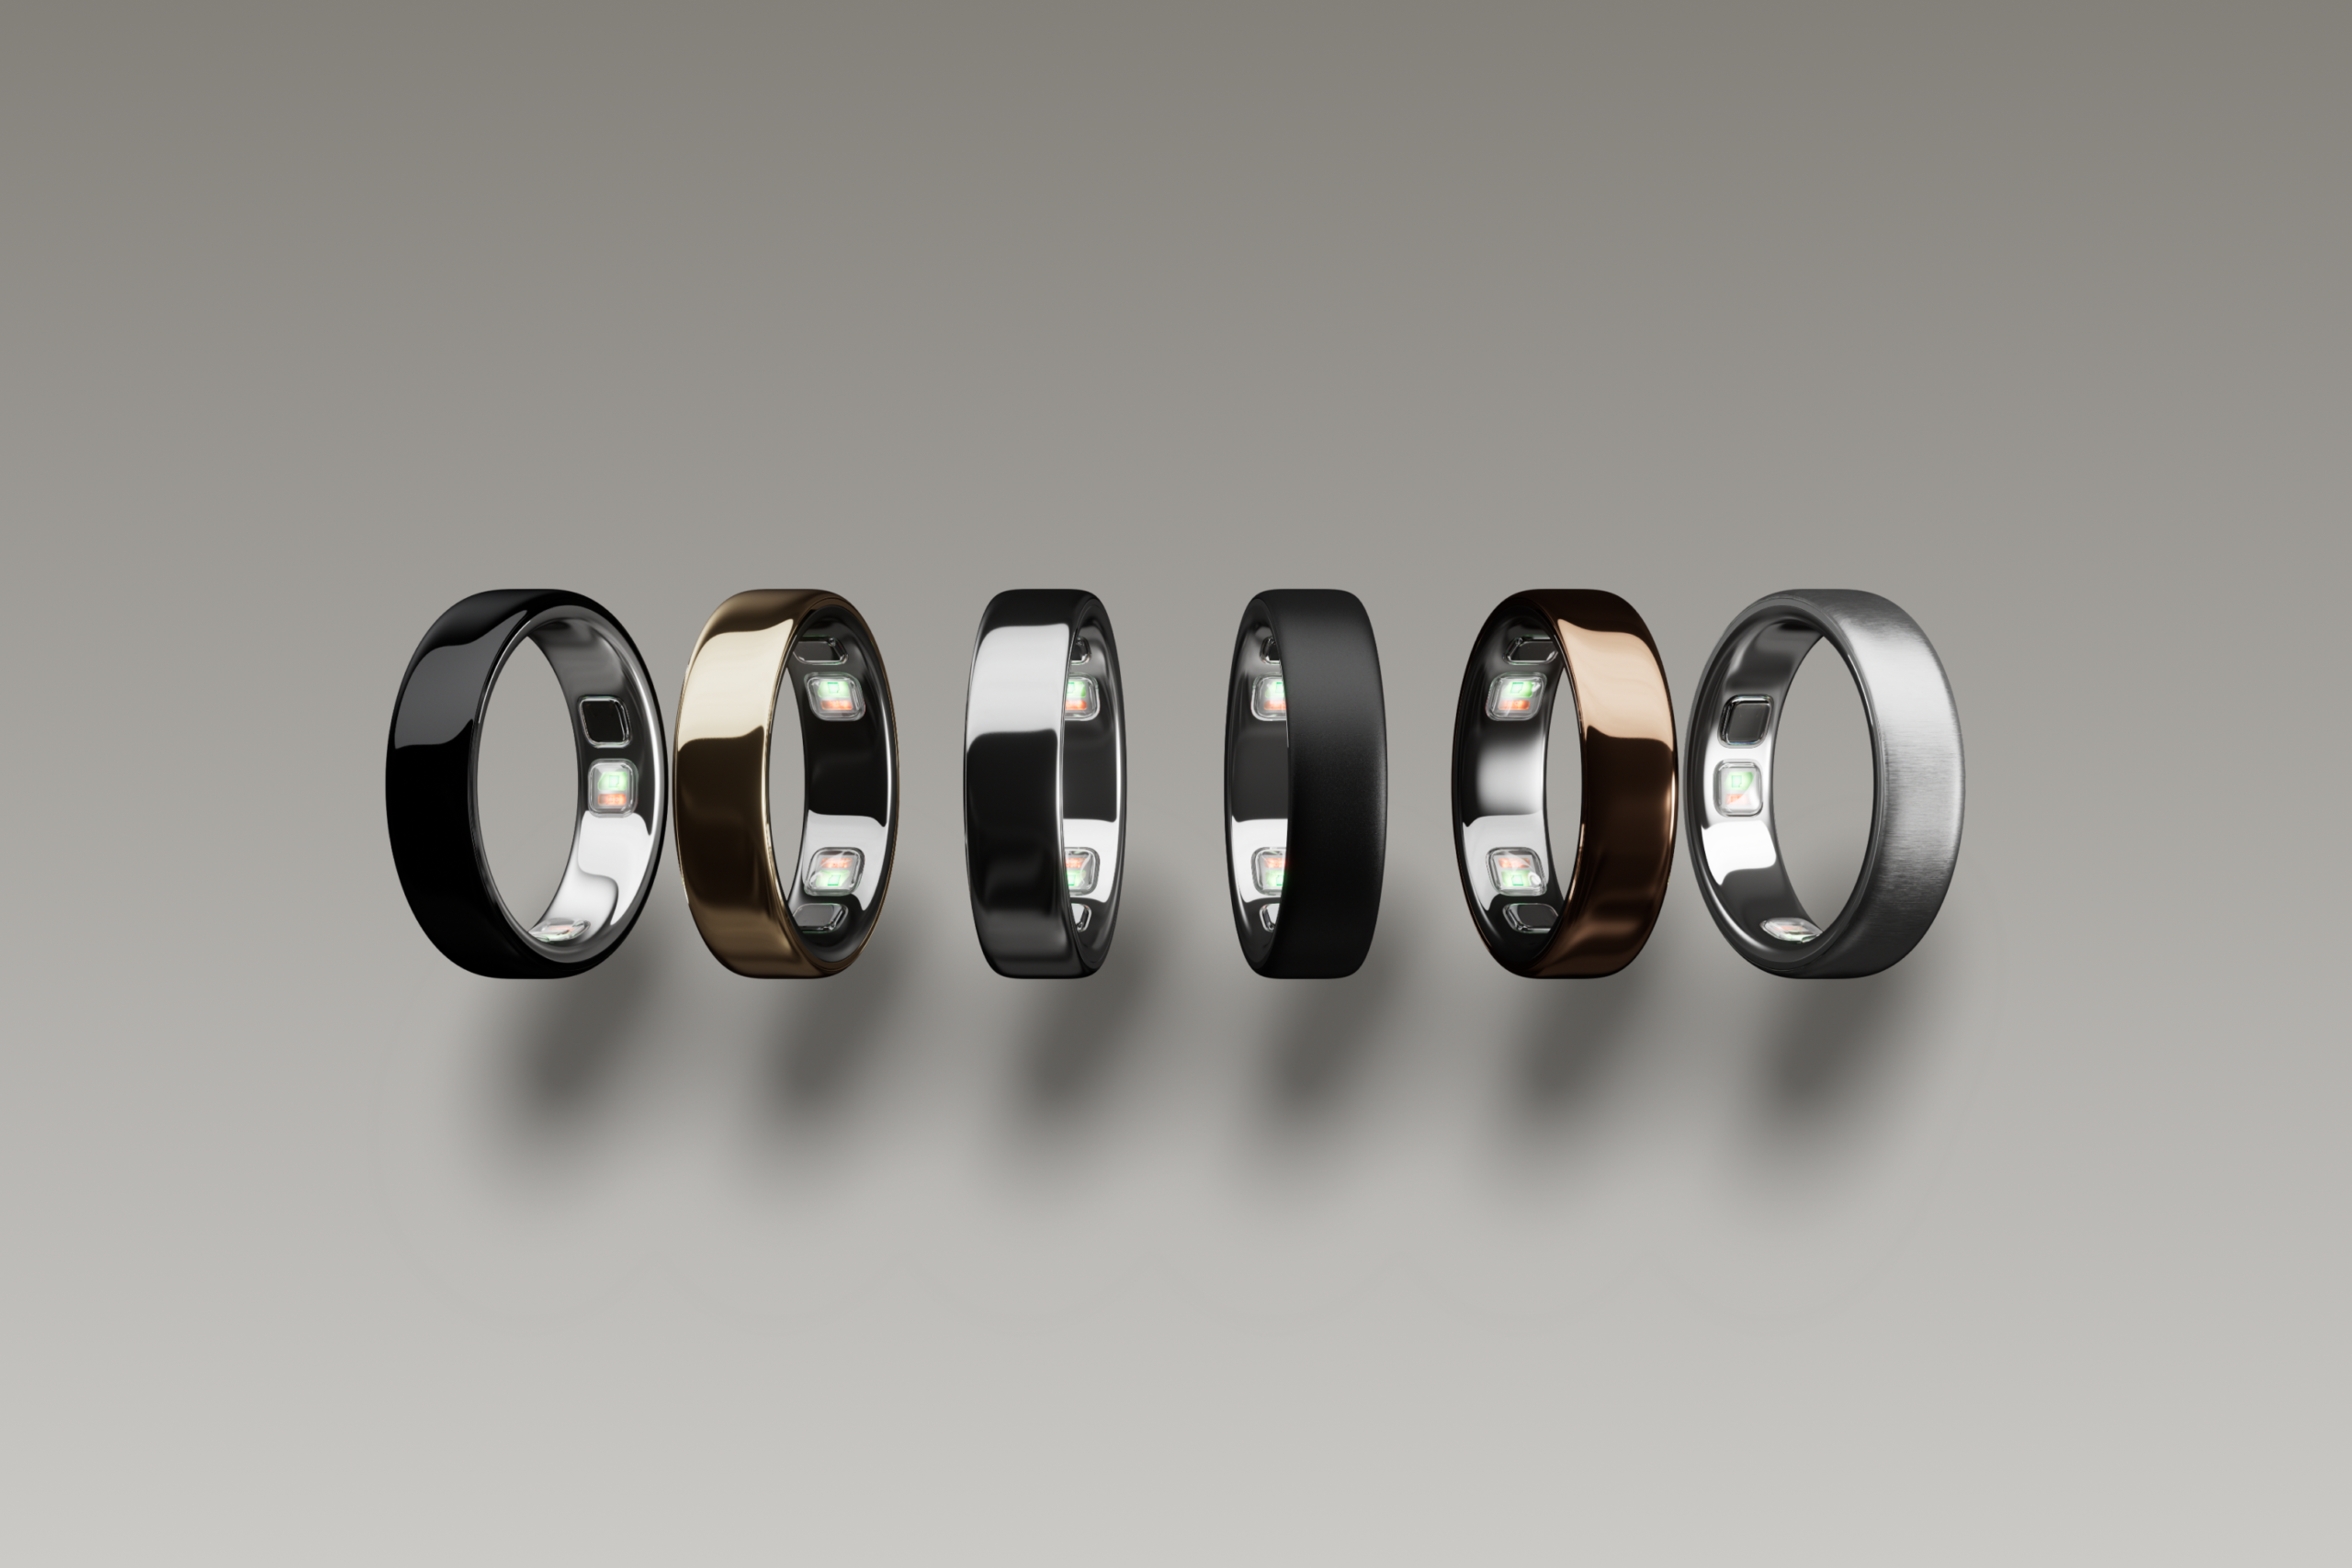
Unlike most IPOs, Oura will not deploy the capital toward growth initiatives, product development, or market expansion. Instead, the company faces a substantial tax obligation tied to employee equity compensation that vests upon the IPO event itself.
The company expects net proceeds of $532.6 million, with $526.4 million earmarked to pay accumulated tax liabilities on employee share grants that become exercisable at the IPO closing. That leaves Oura with approximately $6.2 million for general corporate purposes, less than two percent of the capital ostensibly raised.
This approach reflects Oura’s financial strength and independence. The company maintains roughly $372 million in cash as of the end of June, eliminating any operational need for IPO capital. By using the IPO proceeds to cover the tax liability rather than depleting cash reserves or taking on debt, Oura preserves its balance sheet while meeting an obligation tied to employee compensation. In a sense, the IPO serves as a mechanism for managing a predictable tax liability while simultaneously providing liquidity to investors whose positions have appreciated dramatically.
The Subscription Business Is Accelerating
Oura’s financial trajectory reveals a company in significant growth mode. The membership subscription business has emerged as a major profit center alongside the traditional hardware sales that historically drove revenue.
Revenue acceleration and margins
Membership revenue more than doubled year-over-year to $240.5 million, now representing roughly twenty percent of total company revenue. The gross margin on subscriptions stands at eighty-nine percent, far exceeding typical software-as-a-service margins and reflecting the minimal incremental costs associated with serving each additional subscriber. This margin profile is notable: once users pay for a subscription, Oura’s costs to maintain that relationship are negligible, creating powerful unit economics.
Growing subscriber base
The company projects it will reach 5.7 million paying members by the end of its fiscal year on September 30, nearly doubling the subscriber base from a year earlier. Hardware sales, at $974 million, still comprise the majority of revenue, but the rate of growth in subscriptions—more than doubling annually—signals a fundamental shift in business model composition. This trajectory indicates Oura has moved beyond the early-adopter phase and is capturing mainstream consumer interest in wearable ring technology.
Valuation Growth Across Recent Funding Rounds
Oura’s progression through private funding rounds in recent years demonstrates sustained investor confidence in both the smart ring category and the company’s operational execution.
The company commanded an approximately $5.2 billion valuation in a funding round conducted less than a year before October 2025. Then in October 2025, it raised $900 million at an approximately $11 billion valuation, more than doubling its value in under a year. Fidelity led that round, with participation from ICONIQ Capital, Whale Rock Capital, and Atreides Capital.
If Oura prices at the top of the proposed range of $44 per share, the company would debut at a market capitalization of $14.1 billion, representing another significant leap. Across its entire funding history, Oura has raised approximately $2.06 billion, according to PitchBook data, demonstrating consistent ability to access capital at rising valuations.
Why This IPO Structure Works for Oura
The IPO’s unusual design—functioning as a shareholder exit rather than a corporate capital raise—is possible only because Oura has already achieved profitability and strong cash generation. The company does not require external capital to fund ongoing operations, scale infrastructure, service debt, or accelerate product development. The public market debut instead provides an ordered exit for investors whose initial stakes have appreciated sevenfold or more since the 2020 Series B.
Subscription economics provide durable profit potential
The eighty-nine percent subscription gross margin, combined with an expanding member base locked into recurring annual or monthly charges, creates powerful profit potential. These subscription economics support ongoing investment in customer acquisition, hardware development, and operations without requiring growth capital from an IPO. The business has already demonstrated it can generate cash while scaling subscribers.
A company entering public markets from strength, not necessity
The $6.2 million allocated for general corporate purposes starkly illustrates Oura’s position: a company that has already built a sustainable, profitable business and is entering public markets from strength rather than capital urgency. While most IPOs involve substantial capital raises for future growth initiatives, Oura’s IPO is principally about providing early shareholders—particularly Forerunner Ventures—with a liquidity event, while the company handles a one-time tax obligation created by employee equity vesting. The structure demonstrates a company confident enough in its fundamentals that it can use a major capital event primarily to reward early backers.
Frequently Asked Questions
Why is Forerunner Ventures selling such a large stake in Oura's IPO?
Forerunner is capturing returns on its initial investment in Oura's 2020 Series B funding round when the company was valued far lower. The firm's 9.3% stake is worth approximately $1.2 billion at the IPO price midpoint, representing a substantial multiple on its $28 million Series B investment.
What will Oura do with the money raised in the IPO?
The company will use the majority of its $532.6 million in net proceeds—$526.4 million—to pay accumulated tax obligations from employee share grants that vest at the IPO closing. This leaves only $6.2 million for general corporate purposes, reflecting that Oura is not using the IPO primarily for growth capital.
What is driving Oura's growth?
The company's subscription membership business is expanding rapidly, with revenue more than doubling year-over-year to $240.5 million and maintaining 89% gross margins. The company expects to reach 5.7 million paying members by the end of fiscal 2026, nearly double the prior year, as it moves beyond early adopters into mainstream markets.
